


The bond market just crossed a line investors have watched for years. On Tuesday, September 15, 2026, the U.S. 10-year Treasury yield climbed through the 5% mark — prints around 5.02%–5.04% in major market reports — reaching its highest level since 2007. That is not a trivia fact. The 10-year helps set the tone for mortgages, corporate borrowing, and how expensive “safe” money looks next to stocks.
The timing sharpens the story. The Federal Reserve’s two-day FOMC meeting is underway, with the rate decision due Wednesday, September 16 at 2:00 p.m. ET. Markets have been pricing a high chance of a hike. Even so, long-term yields are already moving on oil, inflation fears, heavy Treasury issuance, and term-premium demand — forces the overnight fed funds rate does not fully control.
10-Year Treasury Yield Hits 5% — Highest Since 2007
Here is what the milestone actually means, what it does not mean for everyday cash accounts, and how to think about bonds, mortgages, and parking money without confusing a 10-year yield with a high-yield savings APY.
- What happened: 10-year yield above 5%, highest since 2007
- Why it matters tomorrow: Fed decision + press conference can still swing the long end
- Who feels it first: mortgage shoppers, bond holders, equity valuations
- Cash reality check: 5% on the 10-year ≠ automatic 5% in your HYSA
The numbers behind today’s bond-market shock
According to Tuesday market coverage from outlets including Bloomberg, Reuters, and Trading Economics, the benchmark 10-year yield pushed above 5% and tagged multi-year highs near 5.02% (with some reports citing intraday peaks near 5.03%–5.04%). That move surpassed the 2023 peak area and took the note to levels last seen in the 2007 cycle.
Why say “highest since 2007” instead of “first time since 2007”? Because the 10-year also briefly touched around 5% in October 2023. The cleaner, defensible claim — and the one major wire headlines are using — is that today’s level is the highest since 2007.
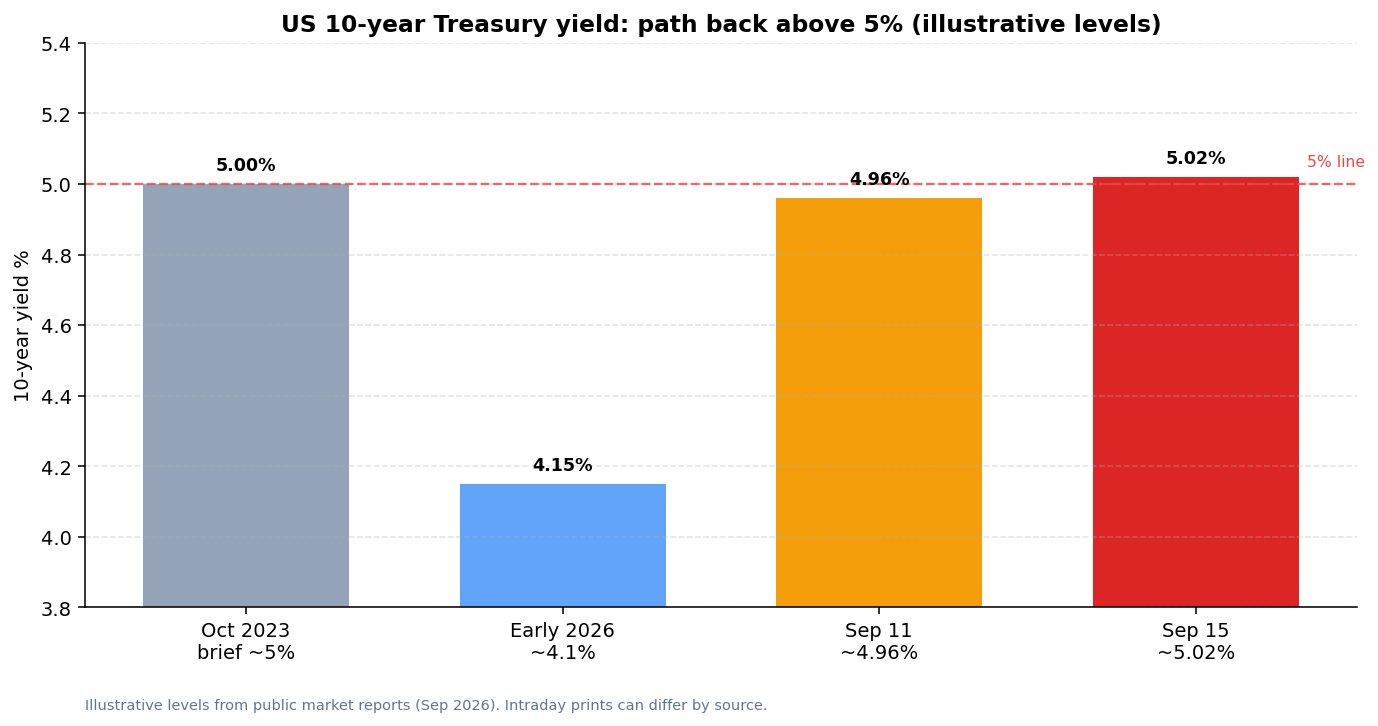
| Checkpoint | Approx. 10-year yield | Why it matters |
|---|---|---|
| Oct 2023 | ~5% brief touch | Prior cycle high area |
| Early 2026 | ~4.1% zone | Much lower starting point this year |
| Sep 11, 2026 | ~4.96% | Already pressing the line |
| Sep 15, 2026 | ~5.02%+ | Highest since 2007 |
Levels are approximate from public market reports and can vary slightly by timestamp and data vendor.
Why yields are rising into a Fed meeting
A Fed hike expectation can support higher front-end rates, but today’s long-end break is a broader cocktail:
- Energy / inflation nerves: higher oil feeds inflation fears and raises the term premium investors demand
- Heavy government issuance: more supply often means buyers want cheaper prices (higher yields)
- Fiscal and debt overhang: markets are pricing persistence, not a one-day scare
- Policy uncertainty into Wednesday: the statement, SEP/dot plot, and chair press conference can reprice the path
As of Tuesday coverage, futures-based odds of a 25 bp hike on Wednesday have been running around the 90%+ area. Important nuance: even if the Fed delivers that hike, the 10-year can still rise or fall depending on whether investors hear “inflation fight” or “growth scare.”
Mortgages: the 10-year matters more than the overnight Fed rate
This is the Norada-relevant piece. A 30-year fixed mortgage is generally priced off the 10-year Treasury plus a mortgage spread, not directly off the federal funds rate. That is why mortgage rates can stay sticky — or rise — even when the Fed is not cutting.
Recent industry coverage into this week has flagged 30-year fixed quotes pushing toward or through the high-6% / ~7% conversation as the 10-year surged. Exact lender quotes move daily, but the mechanism is clear:
| If this moves… | Mortgage shoppers usually feel… |
|---|---|
| 10-year yield ↑ | Upward pressure on 30-year fixed quotes |
| Mortgage spread widens | Rates can rise even if the 10-year is flat |
| Fed hikes overnight rate | Indirect effect — watch the 10-year after the press conference |
- If you are locking a purchase mortgage, compare float vs lock with today’s 10-year path in mind
- If you are waiting for “the Fed to save rates,” remember Wednesday’s overnight decision is not a mortgage remote control
- Watch the 10-year after the 2:00 p.m. ET statement as closely as the headline hike/hold call
What a 5% 10-year does — and does not — mean for cash savers
This is where headlines get sloppy. A 10-year Treasury yield at 5% means the market’s benchmark long rate is there. It does not automatically mean:
- your high-yield savings account just became a locked 5% APY
- every bank will match 5% tomorrow morning
- “cash” and “10-year note” are the same product
Those are different instruments:
| Product | What 5% on the 10-year implies | Liquidity / risk note |
|---|---|---|
| 10-year Treasury note | Market yield around 5% (price moves daily) | Mark-to-market if you sell early |
| Short T-bills | Often related, but not identical to the 10-year | Short maturity, different yield |
| HYSA | Variable bank APY; may lag or diverge | High liquidity; not a Treasury |
| Money market / brokerage cash | Can reprice with policy and competition | Read the yield basis carefully |
Practical cash framing (accurate): when long yields jump and the Fed is poised to tighten, it is reasonable to review where idle cash sits — competitive HYSAs, short Treasuries, or a mix — but pitch it as rate shopping and risk matching, not as a “guaranteed 5% cash window” cloned from the 10-year print.
Stocks and “risk-free” competition
At 5%, Treasuries become a louder competitor to equity valuations. Analysts often treat a sustained move through 5% as a higher hurdle rate for stocks: future cash flows get discounted harder, and “why own risk?” becomes an easier question when government paper yields more. That does not mean equities must crash the day yields tag 5% — earnings, AI capex narratives, and liquidity still matter — but it does raise the bar.
- For long-term investors: expect more volatility around the Fed prints
- For balanced portfolios: bond prices fall when yields rise; duration hurts in a selloff
- For cash allocators: higher benchmark yields strengthen the case to stop leaving large balances in near-zero legacy savings
A same-week checklist before Wednesday’s Fed decision
- Separate the stories: overnight Fed funds vs 10-year yield vs your mortgage quote vs your HYSA APY
- If buying a home soon: get updated lender quotes and ask how they are treating lock extensions into the FOMC window
- If holding long bonds / bond funds: know your duration; a yield spike is a price drop
- If parking cash: compare live HYSA APYs and short bill yields — do not assume they equal the 10-year
- After 2:00 p.m. ET Wednesday: re-check the 10-year first, then mortgage quotes, then deposit rates
Bottom line
The 10-year Treasury yield hitting 5% — the highest since 2007 — is a real bond-market milestone landing less than a day before a highly watched Fed decision. It matters for mortgages, valuations, and the opportunity cost of idle cash. Just keep the labels honest: this is a long-term government yield breakthrough, not a coupon clipped automatically into every savings account. Use the moment to reprice your plan — home financing, bond risk, and cash parking — against live numbers, not against a slogan.
Strong Returns With Turnkey Rentals Despite Fed Uncertainty
The Fed’s rate decisions can create market volatility, but turnkey rentals continue to deliver reliable cash flow and appreciation. Investors in 2026 are focusing on real estate as a hedge against uncertainty.
Norada Real Estate helps you secure turnkey properties designed for immediate income and long‑term growth—so your portfolio stays strong regardless of Fed policy shifts.
🔥 HOT INVESTMENT LISTINGS JUST ADDED! 🔥
Speak with an Investment Counselor Today (No Obligation):
(800) 611-3060
Or Request a Callback / Fill Out the Form Online
Want to Know More?
Explore these related articles for even more insights:
